Partial 1031 Exchange and Boot Management Strategy
Structure the exchange to calculate tax costs before choosing how much cash to take.
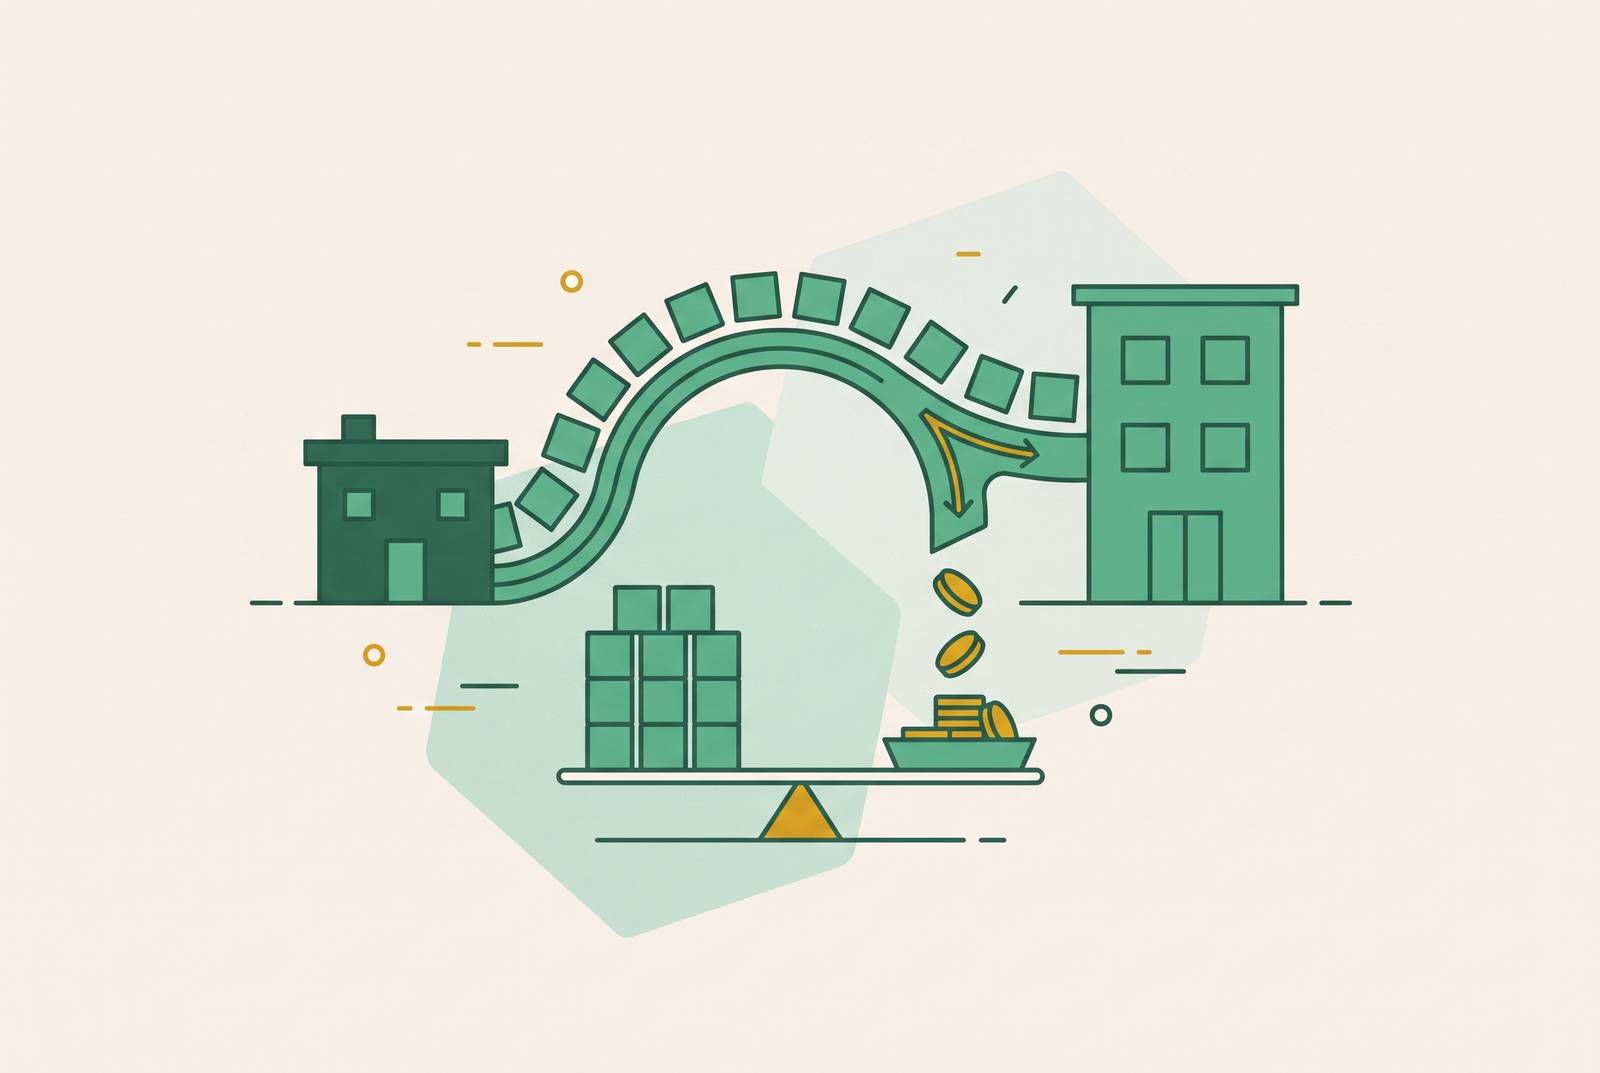
A partial 1031 exchange allows an investor to receive cash or reduce debt while deferring gain beyond the taxable portion, known as boot. The strategy is to calculate cash boot and mortgage boot separately, apply the netting rules, and price the resulting tax before committing to the replacement property.
Why a partial 1031 exchange deserves a strategy, not an apology
Full deferral is a tax objective. An investor may need liquidity, want a smaller or less management-intensive property, or find replacement financing too expensive to justify a dollar-for-dollar reinvestment. A partial exchange accommodates those decisions without necessarily exposing the entire realized gain to tax. The property decision remains central to the transaction. Avoiding boot is useful only when the cost of doing so is justified.
The opposite approach can distort property selection. Treating any taxable boot as a failed exchange can push an investor to buy a worse replacement just to use up the proceeds. It can also lead an investor to abandon an otherwise useful exchange and recognize the entire gain. A value gap does not have to lead to either outcome. The relevant comparison is between the tax cost of a partial exchange and the economic cost of forcing full deferral.
That comparison requires the same calculations whether boot is deliberate or accidental. Taking cash for another investment is a deliberate choice, while paying down debt without accounting for the tax is an oversight. The tax mechanics do not distinguish between those intentions. Planning converts the calculation from a closing surprise into a decision input.
The two conditions for full deferral and what breaks them
Full deferral requires reinvestment of the exchange equity and acquisition of sufficient replacement value. Under the equity test, cash returned by the qualified intermediary, or QI, is boot, with gain recognized up to the realized gain. Under the value/debt test, a cheaper replacement creates a value gap, while reduced debt requires compensating cash. Both tests must be addressed in the exchange structure.
IRC §1031(a)(3) establishes the 45-day identification and 180-day exchange periods, which run concurrently from the relinquished property’s sale. Missing a required deadline jeopardizes exchange treatment, rather than merely creating a planned taxable portion. Control of the proceeds is equally fundamental. Under Treas. Reg. §1.1031(k)-1, the exchange proceeds must go straight to the QI at closing without first going to the investor.
How cash boot and mortgage boot are each calculated
Cash boot begins with proceeds that are not reinvested. In the brief’s $1,000,000 sale example, an investor purchases a lower-priced replacement and receives the unused proceeds from the QI. The returned amount is cash boot. The sale price alone does not establish that amount, because the calculation requires the actual proceeds and their use in the replacement acquisition. Gain recognition remains limited by the gain realized on the relinquished property.
The timing of a cash distribution does not remove its character as boot. Cash deliberately taken from the sale and cash left over after the replacement acquisition both enter the calculation. Some permissible exchange costs can be paid from exchange funds without creating boot, while loan origination fees and prorated rents may create exposure. The QI should sort out which costs fall into each group before closing.
Mortgage boot starts with a different comparison. Treas. Reg. §1.1031(d)-2 treats liabilities discharged in the exchange as money received by the taxpayer. When the relinquished property has a larger mortgage than the replacement, the reduction establishes the debt-relief amount before applicable offsets. An investor who reinvests every dollar of equity can therefore still have mortgage boot because the exchange has relieved an obligation.
How cash boot and mortgage boot are netted — and why the asymmetry matters
Treas. Reg. §1.1031(b)-1 and §1.1031(d)-2 set the rules for how cash and debt relief work together. Personal cash contributed to the exchange can offset mortgage boot dollar-for-dollar. But borrowing more against the replacement cannot offset cash boot. The direction of the offset is decisive. A financing plan that ignores this asymmetry can preserve a taxable cash distribution even when the replacement loan is larger.
Consider the investor moving from a higher mortgage to a lower mortgage. The first step is to subtract the replacement debt from the discharged debt. That difference is the mortgage boot exposure before compensating cash. Next, the investor works out how much personal cash went into the exchange on top of the reinvested exchange equity. Those additional funds reduce the debt-relief exposure dollar-for-dollar, and an equivalent contribution eliminates it.
The contribution must be additional to the exchange equity. Merely reinvesting the proceeds already held by the QI does not constitute the extra cash needed to compensate for reduced debt. The investor is using personal capital to supply value that the smaller replacement mortgage does not provide. Using personal cash this way can keep full deferral intact even with less debt.
The reverse transaction produces a different result. An investor who receives cash cannot cancel that receipt by borrowing more against the replacement property. The distribution remains cash boot despite the additional liability. This is also why a post-exchange cash-out refinance differs from taking cash through the exchange. A refinance after completion is not itself a taxable event and can provide liquidity without an exchange distribution.
After the applicable netting, recognized gain is limited to the lesser of boot received or total realized gain. If boot is $100,000 but the relinquished property’s realized gain is lower, recognition cannot exceed that actual gain.
How boot is taxed — recapture priority, capital gains, and NIIT
The recognized amount may be taxed at more than one capital gains rate. The underlying gain determines its tax character. For depreciated rental real estate, the first layer is unrecaptured §1250 gain associated with accumulated straight-line depreciation, followed by remaining long-term capital gain. That ordering can make a modest distribution comparatively expensive. If the depreciation-related gain pool is large enough to cover the entire recognized amount, none of that amount gets the lower capital gains treatment.
IRC §1(h) governs the preferential rates applicable to the remaining long-term capital gain according to the investor’s income bracket. Net investment income tax, or NIIT, can add to the tax bill when it applies. These are not interchangeable categories or rates simply added to all boot. The estimate must allocate recognized gain by character and then assess NIIT exposure. Changing the exchange structure does not turn the underlying gain into a different type of income.
State treatment further changes the after-tax result. California taxes capital gain as ordinary income, while New York recognizes §1031 deferral but taxes recognized gain under its state rules. Florida has no state income tax. The federal calculation is therefore not the complete bill. Residence and applicable state treatment belong in the estimate, rather than being considered after the investor has selected a cash distribution.
Five planning moves that reduce or manage recognized gain from boot
For investors translating these mechanics into a plan, the first move is to trade equal or up on value and debt while reinvesting all exchange equity. This is the most direct route to avoiding boot. It requires property selection and financing to work together before closing. Its limitation is economic rather than mechanical, because the replacement must still justify its price and debt burden.
The second move is to contribute personal cash when the preferred replacement has less debt. The contribution offsets mortgage boot dollar-for-dollar. This approach allows the investor to select a lower-debt structure without treating the resulting debt relief as unavoidable taxable boot. It does, however, consume liquidity. The contribution’s tax benefit is limited to reducing boot.
The third move is an improvement exchange, also called a build-to-suit exchange. When the replacement’s value is insufficient but the property can be improved, exchange proceeds can fund construction within the 180-day window. Completion and transfer timing constrain the strategy. The improvements must be substantially completed and title transferred to the investor within that period. Specific structuring requirements apply, so the QI must manage the exchange process rather than treating the work as an ordinary post-acquisition renovation.
The fourth move is to use a Delaware Statutory Trust, or DST, to fill a remaining value gap. Qualifying DST interests let the investor own a fraction of a like-kind replacement and invest the leftover proceeds without having to find another whole property at exactly the right price. Identification timing still governs their usefulness. A DST can also serve as a backup identified within the 45-day window if the primary replacement falls through.
The fifth move addresses the tax cost of boot that remains. Cost segregation on the replacement can produce accelerated depreciation deductions, and suspended passive losses may also change the net tax owed. Neither is an automatic dollar-for-dollar tax offset. Their usefulness depends on whether the deductions are available against the recognized income under the applicable limitations. In particular, boot recognition should not be treated as automatically releasing all suspended losses under §469(g)(1)(A). The CPA should determine the usable deductions before the investor decides how much boot to accept.
Common mistakes that create accidental boot
Buying down while tracking only equity reinvestment leaves the replacement-value test unexamined. The investor may complete the purchase with all available exchange cash and still discover taxable exposure from the smaller acquisition. The error occurs during property selection as well as at closing.
Taking a smaller replacement loan just because the cash flow supports a smaller balance can lead to surprise mortgage boot. Without a planned contribution of personal cash, the financing decision leaves uncompensated debt relief. A smaller loan is not automatically tax-neutral.
Treating every closing charge as a permissible exchange expense can turn disbursements into unexpected boot. Loan origination fees and prorated rents require attention before exchange funds are committed. Settlement accounting is part of the tax structure.
Refinancing the relinquished property to extract cash immediately before an exchange invites a different risk. The IRS may scrutinize whether the refinancing occurred in contemplation of the exchange and treat the proceeds as boot.
Failing to extend a tax return can shorten the completion window for a fourth-quarter sale. Under IRC §1031(a)(3)(B), the return due date can end the exchange period before the full 180 days have elapsed unless an extension is filed. The result may be a premature closing or an incomplete exchange.
When accepting boot is the right decision
Accepting boot can be the better economic choice when liquidity has greater value than the associated tax cost. Capital needed for a business venture, improvements to another property, or a personal obligation may justify a taxable distribution. The comparison is with the actual financing alternative. Likewise, when the best replacement costs less, paying tax on modest boot can be preferable to overpaying for an inferior asset merely to reach full deferral.
A QI for a partial exchange should explain boot clearly, open the exchange promptly, and hold funds securely. Concrete selection criteria include openly published rates, segregated federally insured accounts, and a single senior exchange officer. Those features support a transaction in which the QI controls proceeds, cash-release timing, and accounting for Form 8824. They do not replace the CPA’s tax analysis.
Before signing a purchase agreement, the investor should have the CPA calculate cash boot, net mortgage boot, the depreciation-related gain allocation, NIIT exposure, and available deductions. The QI should coordinate the proceeds and closing structure with that plan. Intentional boot is a legitimate planning choice. The discipline is to know the number before closing.